Structured Notes
Market Growth Potential with Built-In Protection
What Are Structured Notes?
A Hybrid of Bonds and Market-Linked Growth
Structured notes are hybrid investments issued by some of the world’s largest banks. They pair a bond-like structure with a return linked to a market index or other asset, and they spell out the risk and return terms before you invest. Through direct relationships with issuing banks, we can custom-structure notes around a client’s specific goals, risk tolerance and market outlook.
Key Features
The nuts and bolts
Maturity
Terms range from 6 months to 20 years, so a note can be matched to your time horizon.
Underlying Assets
Returns are linked to stocks, indexes, commodities, currencies, interest rates or other asset classes.
Return Potential
Income through periodic payments, or growth paid as a capital gain at maturity.
Protection
Barrier and buffer features help limit losses, and principal-protected notes safeguard your investment while keeping market participation.
Deferred Notes
Returns are delayed until a specific date, allowing for potential growth and tax advantages during the deferral period.
Income Notes
Built to generate regular payments, often tied to the performance of assets like stocks or bonds.
How Structured Notes Work
Working with your advisor
- Choose your goal. Steady income (an income note) or capital growth (a deferred note).
- Pick an asset. Your note is tied to an underlying asset, like an index or a specific stock.
- Set the terms. Define your level of protection, your term and your return expectations.
- Hold to maturity. Notes are designed to be held until they mature, when the outcome is calculated.
Barrier Notes
- Protection is conditional on the underlying asset staying above a preset level.
- Higher return potential when markets are stable.
Buffer Notes
- Partial protection against declines, up to a set percentage.
- A fit for investors who can tolerate minor losses while aiming for growth.
An example
Karen L. and a Dual Directional Buffer Note
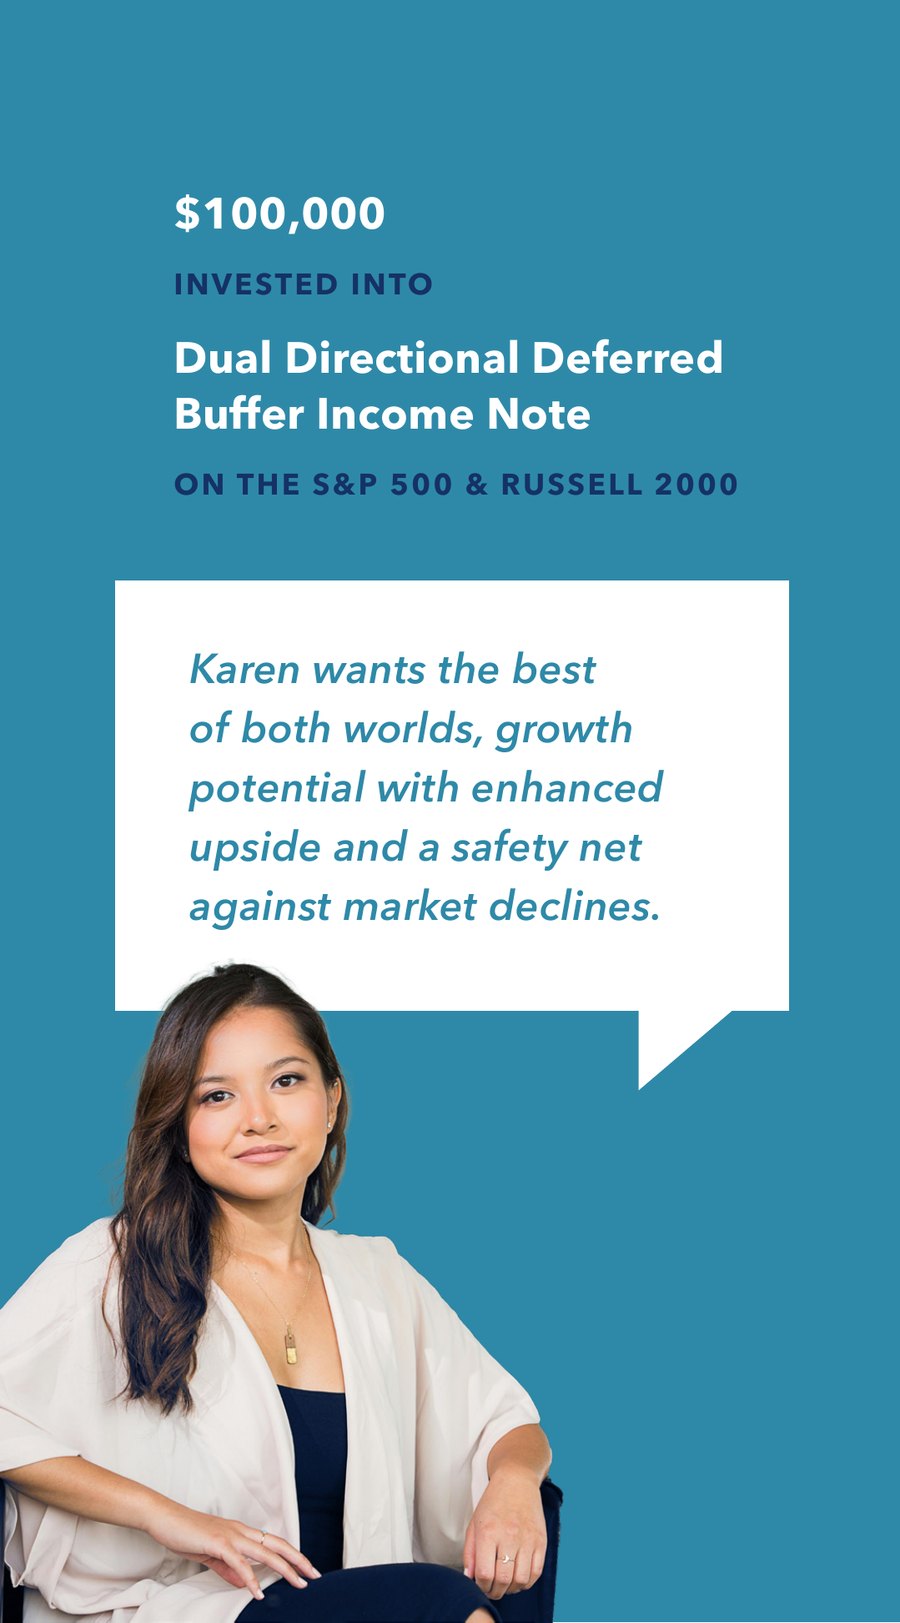
Karen wants growth potential with a safety net against market declines. She invests $100,000 in a Dual Directional Deferred Buffer Income Note linked to the S&P 500 and the Russell 2000.
Illustrative Outcomes at Maturity
| If the index is | Karen’s note returns | Value of $100,000 |
|---|---|---|
| Up 25% | +20% | $120,000 |
| Up 10% | +10% | $110,000 |
| Flat, 0% | 0% | $100,000 |
| Down 20% | +20% | $120,000 |
| Down 25% | -5% | $95,000 |
Returns are total returns over 24 months, not annualized, and are based on the worst-performing of the two indexes. This is a hypothetical example for illustration only. It is not a guarantee or projection of future results. Payments depend on the creditworthiness of the issuing bank.
Upside
If the index rises, Karen receives 100% of that growth, up to 20%. A 20% gain is a $20,000 return.
Downside
If the index falls by up to 20%, Karen receives that amount as a positive return. If the decline is more than 20%, her loss starts at the 20% mark. A 30% decline is a 10% loss.
Tax treatment
The gain or loss at maturity is treated as a capital gain and, if the note is held to maturity, may qualify for long-term capital gains rates.
Free Guide
Structured Notes: A Simple Guide for Investors
Download our 16-page guide to how structured notes work, with three illustrated examples.
Understand the Risks
What to weigh first
Liquidity risk. Structured notes are designed to be held until maturity. Selling early may mean finding a buyer or accepting a significant discount.
Market risk. Returns depend on the underlying asset. Poor performance can reduce returns or cause losses, depending on the level of protection built in.
Issuer default risk. A note is only as strong as the bank behind it. If the issuing bank fails, you could lose principal and returns.
Structured notes may be suitable for investors who:
- Want customized solutions for specific investment goals.
- Value partial protection in volatile markets.
- Have a moderate to high understanding of investment products.
Your Questions, Answered
What is a structured note?
It is an investment issued by a bank that pairs a bond-like structure with a return linked to a market index or other asset. The terms, including any protection, are set before you invest.
What is the difference between a barrier and a buffer?
A barrier protects you only if the underlying asset stays above a preset level. A buffer absorbs losses up to a set percentage, and you take on losses beyond it.
Can I lose money?
Yes. Losses are possible if the market falls beyond the note’s protection, if you sell before maturity, or if the issuing bank defaults.
Can I get my money out before maturity?
Structured notes are designed to be held to maturity. Selling early may be difficult and can mean accepting a lower price, so we only use them for money you will not need during the term.
How are structured notes taxed?
It depends on the note. In the example above, the gain or loss at maturity is treated as a capital gain. We review the tax treatment of each note with you, and you should confirm it with your tax professional.
What are the fees?
Costs vary by note and are disclosed in each note’s offering documents. We walk through them with you before you invest.
Could a Structured Note Fit Your Plan?
Let’s look at your goals, your time horizon and how much protection you want, then see whether a note makes sense.
Structured notes are complex products and are not suitable for every investor. They are subject to market, liquidity and issuer credit risk, and you can lose some or all of your principal. Examples are hypothetical and for illustration only.